
Tax Brief: Form 990, Schedule G — Fundraising and Gaming Activities
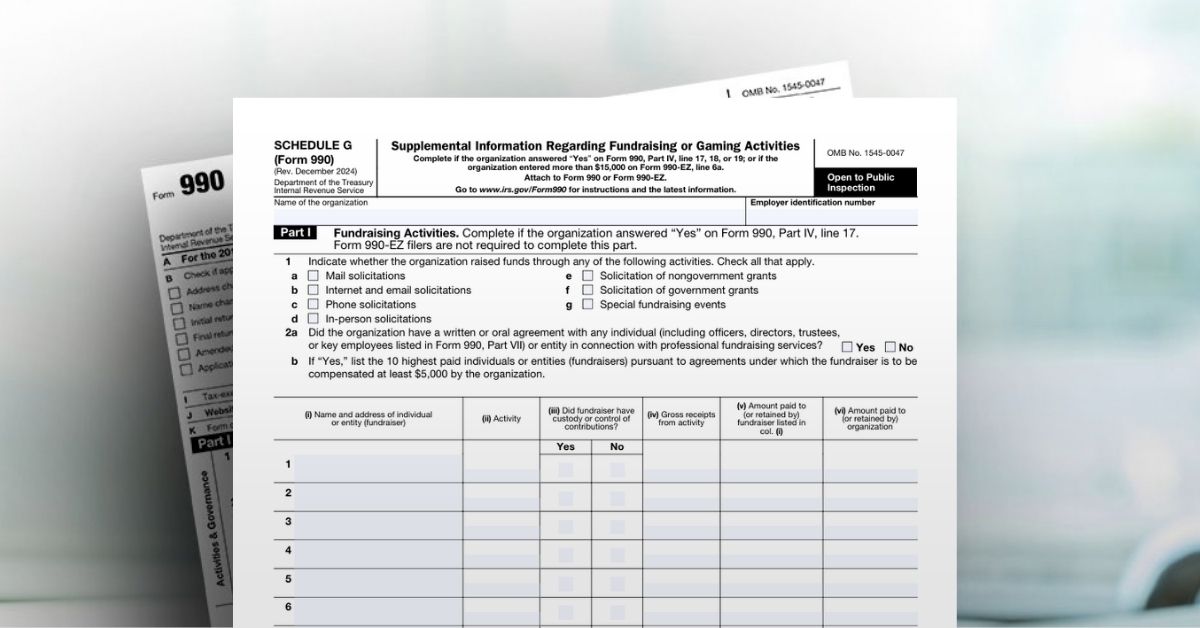
The IRS Form 990, Schedule G provides information about an exempt organization’s fundraising activities and events, including benefit dinners and auctions. The schedule also covers gaming activities conducted by the organization, such as bingo, pull-tabs, raffles, casino nights, card games, or video gaming activities. This article will explore the relevant reporting requirements for each part of Schedule G and the related information that must be tracked and reported.
Part I – Fundraising Activities
Did your organization pay an outside professional fundraising service to help raise funds during the fiscal year? If so, there’s a good chance Part I of Schedule G must be completed. The requirement to complete Part I is triggered if the organization 1) files Form 990 (Form 990-EZ filers are not required to complete Part I) and 2) reports more than $15,000 of expenses for professional fundraising services. If both conditions are met, the organization must provide additional information, including the types of activities the organization engaged in to solicit funds (i.e. phone solicitations, mail solicitations, special events, etc.). Organizations must also disclose whether they had written or oral agreements with professional fundraisers, report information for the highest-paid fundraisers receiving at least $5,000 of compensation and list the states in which they are registered or licensed to solicit contributions (or exempt from such registration).
Part II – Fundraising Events
The Fundraising Events portion of Schedule G (Part II) is the section that most broadly applies to exempt organizations. Part II is required to be completed if the organization reports more than $15,000 of fundraising event gross income and contributions during the fiscal year, regardless of whether the organization is a Form 990 or Form 990-EZ filer. Each fundraising event with more than $5,000 of gross receipts during the fiscal year should be tracked separately. The organization must track and report for each event the gross receipts and the amount of contributions/donations included in the gross receipts amount for the fiscal year. Additionally, expense information for each event must be reported, including amounts for cash prizes, non-cash prizes, rent/facility costs, food and beverages, entertainment, and any other direct event expenses. The IRS requires separate reporting of fundraising events with gross receipts greater than $5,000, but the form provides space to report only the two largest events individually; all remaining events are combined and reported as “Other Events” with details reported on Schedule O.
Part III – Gaming
Part III is required to be completed if the organization reports more than $15,000 of gross income from gaming activities. Each type of gaming activity should be tracked and reported separately in Part III. Additionally, expense information for each gaming type must be reported, including cash prizes, non-cash prizes, rent/facility costs, and any other direct expenses. Organizations conducting gaming activities may also be required to answer additional questions regarding gaming management companies, allocation of gaming proceeds, and compliance with applicable state laws and regulations.
In many cases, gaming is regulated by state and local authorities in the jurisdiction in which the activity occurs. Additionally, gaming that is carried on for profit may be considered an unrelated trade or business activity and trigger unrelated business taxable income. Organizations are strongly advised to research state and local laws and consult a tax advisor before engaging in any type of gaming activity.
The purpose of this article is to summarize the major components and reporting requirements of Schedule G and is not intended to be all encompassing or serve as replacement for the Form’s instructions.
This article is meant to be a resource and provide tools to assist your organization. Please consult your tax advisor regarding your specific tax situation.


